How to Start an Investment LLC

This article provides general information for educational purposes only. It is not legal advice, does not create an attorney-client relationship, and should not be relied upon as a substitute for consultation with a qualified attorney. Laws vary by state, and individualized guidance is recommended.
Learn when an investment LLC makes sense, what legal risks to watch for, and the steps to form and operate one properly.
Disclaimer: This article provides general information for educational purposes only. It is not legal advice, does not create an attorney-client relationship, and should not be relied upon as a substitute for consultation with a qualified attorney. Laws vary by state, and individualized guidance is recommended.
To start an investment LLC, first decide whether the structure fits your investment activity and whose money it will hold. Verify the selected state's rules, document ownership and decision-making authority, complete the state filing and applicable tax/EIN steps, and establish separate accounts and records. If passive investors or paid investment management are involved, obtain securities-law review before soliciting or accepting funds.
The filing is only one part of the decision. This guide helps you identify your situation, work out what the LLC would accomplish, and choose whether to proceed, prepare or pause for specialist review.
Before choosing a route, identify the state and operating locations; whose money, assets, debt or proposed transfers are involved; whether participants are active or passive and anyone will be paid to manage or advise; and the owner count, proposed tax treatment, contributions, trading authority, withdrawals and exits. Mark unresolved questions for the relevant adviser rather than treating missing facts as settled.
Choose Your Investment LLC Route
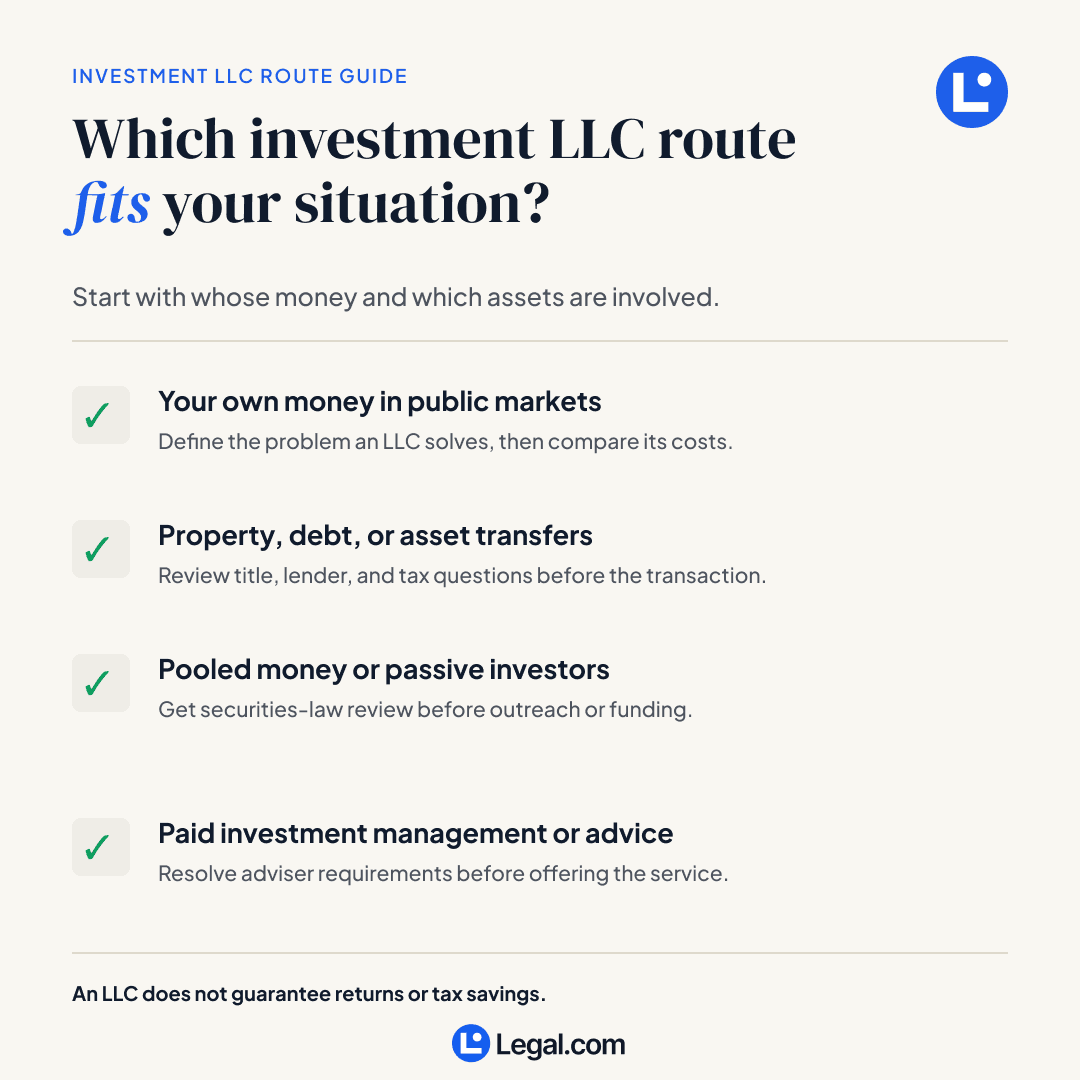
You can explore forming an LLC to hold investments, including a single-owner arrangement. Whether it is suitable depends on your activities and the governing rules—not simply on the value of your portfolio. Start with the route that describes the money and assets involved.
Your situation | The decision to resolve | Your next action |
|---|---|---|
You invest only your own money in public-market investments | What legal, ownership or operational problem would an entity solve beyond holding investments? | Compare the entity's purpose and costs with keeping the existing arrangement. Proceed only once you can explain its value. |
You intend to hold property, use debt or transfer existing assets | What ownership, liability, lender, title and tax questions must be reviewed before the transaction? | Prepare an asset-and-debt inventory and obtain appropriate legal/tax review before transferring assets or signing financing documents. |
You pool capital, involve passive investors or charge for investment management | Who participates, who selects investments, and what securities or adviser questions arise? | Pause solicitation and funding until qualified counsel has assessed the proposed arrangement. |
You invest only your own money in public-market investments
What legal, ownership or operational problem would an entity solve beyond holding investments?
Compare the entity's purpose and costs with keeping the existing arrangement. Proceed only once you can explain its value.
You intend to hold property, use debt or transfer existing assets
What ownership, liability, lender, title and tax questions must be reviewed before the transaction?
Prepare an asset-and-debt inventory and obtain appropriate legal/tax review before transferring assets or signing financing documents.
You pool capital, involve passive investors or charge for investment management
Who participates, who selects investments, and what securities or adviser questions arise?
Pause solicitation and funding until qualified counsel has assessed the proposed arrangement.
These routes can overlap. For example, a property purchase funded by passive participants belongs in both the property and pooled-capital reviews. Do not let a property label obscure whose money is being managed.
Write down three answers before choosing a formation service: what problem the LLC addresses, whose money it will hold, and what it will cost to operate. If an answer is unclear, preparing the facts is a useful next step; filing immediately is not the only outcome.
What Problem Would the LLC Solve?
Separate investment risk from the legal and ownership questions you want to address. An entity-choice decision is not an investment-return strategy, and the promise of liability protection needs a state-specific explanation rather than a blanket assurance.
The disadvantages to assess include setup and continuing costs, additional records, shared decision-making constraints and any obligations arising from the proposed activity. Which is the biggest disadvantage depends on your situation; compare the actual burden with the problem the entity would address.
For a bounded example, Delaware's LLC Act, § 18-303, generally does not make someone personally responsible for LLC obligations solely because they are a member or manager; it also permits an agreement to personal liability. That is a Delaware example, not a statement of every state's rules or protection against every claim.
The problem you identify | What to investigate | What not to assume |
|---|---|---|
Concern that investments may lose market value | Investment selection and risk planning, separately from entity choice | Forming an LLC guarantees returns or prevents portfolio losses |
Property, contractual or operational exposure | Ownership, insurance, contracts, guarantees and applicable liability rules | A filing alone resolves every personal exposure |
Several people sharing an investment | Contributions, ownership, economics, authority and exits | Agreement on an ownership percentage answers every money/control question |
Desire for a tax advantage | Applicable tax classification and the actual proposed transactions | The LLC label automatically produces tax savings |
Concern that investments may lose market value
Investment selection and risk planning, separately from entity choice
Forming an LLC guarantees returns or prevents portfolio losses
Property, contractual or operational exposure
Ownership, insurance, contracts, guarantees and applicable liability rules
A filing alone resolves every personal exposure
Several people sharing an investment
Contributions, ownership, economics, authority and exits
Agreement on an ownership percentage answers every money/control question
Desire for a tax advantage
Applicable tax classification and the actual proposed transactions
The LLC label automatically produces tax savings
Insurance, personal accounts, trusts and LLCs address different questions; they are not interchangeable substitutes. Ask the relevant adviser to explain the problem each option would solve in your circumstances, rather than comparing them only by price or marketing claims.
For a solo investor, the useful question is not “How large must my portfolio be?” but “What changes if I use an entity, and why would that change be worthwhile?” There is no portfolio threshold supplied by this guide.
Before Money Moves: Check These Review Triggers
Review the actual arrangement before relying on its name. Friends, relatives and business partners can have very different roles, and familiarity does not establish the legal treatment of their participation.
The SEC's investment-club bulletin explains that membership interests may be securities and that even one passive member may raise securities issues. It also discusses adviser questions when someone is paid for advice or one person selects investments. These are fact-specific federal and state issues, not an automatic rule that every shared investment needs registration.
Fact to disclose to counsel | The question to resolve | Timing |
|---|---|---|
A participant supplies money but does not actively participate in investment decisions | Does the arrangement involve securities, and what requirements apply? | Before solicitation or accepting their contribution |
Someone will receive management, performance or advice compensation | Do investment-adviser or other requirements apply? | Before offering the paid arrangement |
You plan to advertise or solicit participation | What may be offered, to whom, and with what disclosures? | Before outreach |
Assets, debt or an existing property will move into the entity | What legal, tax, title, lender or institution conditions need review? | Before signing or transferring |
A participant supplies money but does not actively participate in investment decisions
Does the arrangement involve securities, and what requirements apply?
Before solicitation or accepting their contribution
Someone will receive management, performance or advice compensation
Do investment-adviser or other requirements apply?
Before offering the paid arrangement
You plan to advertise or solicit participation
What may be offered, to whom, and with what disclosures?
Before outreach
Assets, debt or an existing property will move into the entity
What legal, tax, title, lender or institution conditions need review?
Before signing or transferring
These are review checkpoints, not a measured low/medium/high risk scale. Active involvement, family relationships or a small group should not be presented as universal securities exemptions. Filing an LLC does not settle those separate compliance questions.
The question “Why don't investors like LLC?” can refer to startup fundraising rather than an entity holding investments. Clarify which investors and which transaction are involved. Do not infer that investors generally reject LLCs, or select a structure for your own portfolio based on an unrelated fundraising preference.
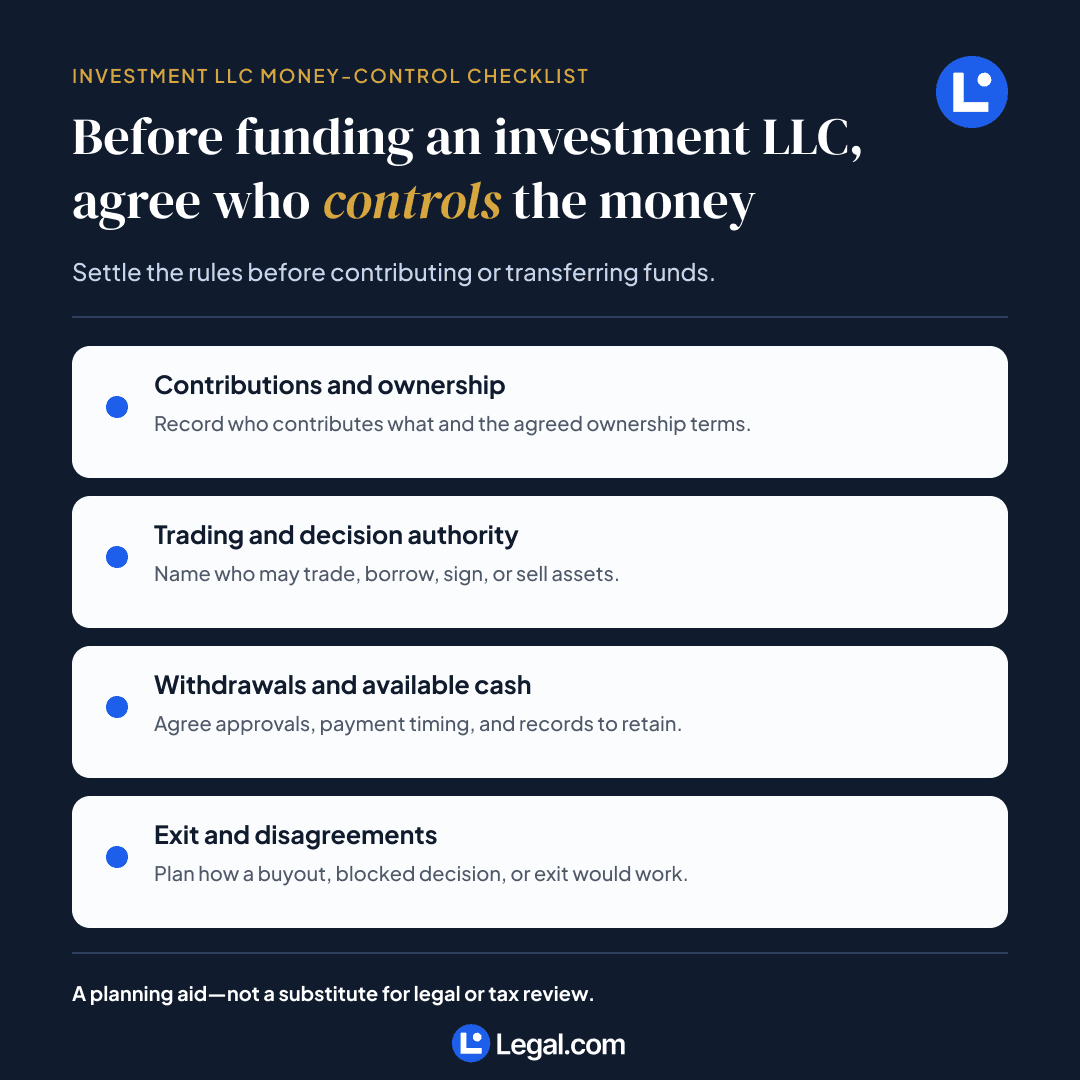
Agree Who Can Contribute, Trade, Withdraw and Leave
A useful operating agreement starts with decisions, not just a downloaded document. Use the following matrix to prepare the terms for legal and tax review. It is an editorial planning aid, not a list of mandatory provisions in every state.
Decision | What the participants should settle | A practical test |
|---|---|---|
Capital | Who contributes cash or assets, when, and how contributions are recorded | Can everyone identify the agreed contribution and its status? |
Ownership and economics | Ownership interests, proposed allocations and distribution expectations | Have you separated ownership, economic terms and tax treatment rather than assuming they are identical? |
Trading and management authority | Who may open accounts, trade, borrow, sign or sell assets | Can the institution and other owners identify the authorized decision-maker? |
Additional funding | How requests for more capital will be decided and handled | What happens if one person cannot or will not contribute more? |
Withdrawals and liquidity | Who approves payments, when funds may leave and what records are required | What happens if an owner needs cash while the assets cannot readily be sold? |
Exit and disagreement | Valuation, buyout process, decision deadlock and proposed dissolution terms | What happens if one owner wants out or the decision-makers disagree? |
Capital
Who contributes cash or assets, when, and how contributions are recorded
Can everyone identify the agreed contribution and its status?
Ownership and economics
Ownership interests, proposed allocations and distribution expectations
Have you separated ownership, economic terms and tax treatment rather than assuming they are identical?
Trading and management authority
Who may open accounts, trade, borrow, sign or sell assets
Can the institution and other owners identify the authorized decision-maker?
Additional funding
How requests for more capital will be decided and handled
What happens if one person cannot or will not contribute more?
Withdrawals and liquidity
Who approves payments, when funds may leave and what records are required
What happens if an owner needs cash while the assets cannot readily be sold?
Exit and disagreement
Valuation, buyout process, decision deadlock and proposed dissolution terms
What happens if one owner wants out or the decision-makers disagree?
For example, two participants might agree to contribute equally but have different expectations about trading authority or access to cash. Resolving those expectations before funding is more useful than discovering them after an investment has been made.
A solo owner can also document contributions, account authority and intended operations. Confirm the selected state's agreement requirements and have proposed economic and tax terms reviewed rather than treating the matrix as legal drafting instructions.
Build a State-Specific Cost Plan
Use verified costs for your proposed arrangement, not a generic national total. For each item below, record the amount, source, date checked, whether it applies, and payment timing. Request a quote where the cost is professional or institution-specific.
Cost category | Where to verify it | What to record |
|---|---|---|
Initial state filing | The selected state's official filing office | Current fee, required filing and any selected optional processing service |
Registered-agent arrangement | State eligibility rules and any provider quote | Eligibility and any service charge; distinguish government and provider costs |
Continuing state obligations | Applicable official state guidance | Which reports, charges or taxes apply and the verified due dates |
Accounts, records and tax preparation | The chosen institutions and tax adviser | Account conditions, recordkeeping needs and quoted preparation costs |
Legal or securities review | Appropriate counsel | Scope, quoted cost and any ongoing review needs |
Additional jurisdictions or asset transactions | Relevant state offices and transaction advisers | Whether additional registration, transaction or compliance costs apply |
Initial state filing
The selected state's official filing office
Current fee, required filing and any selected optional processing service
Registered-agent arrangement
State eligibility rules and any provider quote
Eligibility and any service charge; distinguish government and provider costs
Continuing state obligations
Applicable official state guidance
Which reports, charges or taxes apply and the verified due dates
Accounts, records and tax preparation
The chosen institutions and tax adviser
Account conditions, recordkeeping needs and quoted preparation costs
Legal or securities review
Appropriate counsel
Scope, quoted cost and any ongoing review needs
Additional jurisdictions or asset transactions
Relevant state offices and transaction advisers
Whether additional registration, transaction or compliance costs apply
Then total initial costs, recurring costs and conditional costs separately. Decide who will pay them and whether the arrangement has the resources to continue after formation. Do not treat investment gains as guaranteed funding for future obligations.
This worksheet intentionally does not supply nationwide fees or deadlines. A charge that applies to one state, tax classification or transaction may not apply to another. Include only verified applicable items in your own total.
Form and Fund the LLC in the Right Order
Once the route, review conditions and essential ownership decisions are resolved, organize formation around the actual requirements. IRS LLC guidance identifies LLCs as state-law structures and explains default federal tax classifications; state instructions control the specific formation filing.
Verify State and Naming Requirements
Identify the state of formation and the locations involved, including where the investment property or business activity is located. Ask whether the planned activities require registration elsewhere; do not assume every out-of-state asset creates the same obligation.
Use the official state instructions to check the name, required filing information and registered agent arrangement. There is no universal “easiest LLC” or best state supplied here. The simpler route is the one that fits the governing facts without adding avoidable obligations.
File and Document Ownership
Complete the applicable state filing and confirm its effective status. Do not confuse payment to a service with confirmation that the entity exists. As a specific example, Delaware § 18-201 addresses creation through certificate filing and distinguishes that step from agreement terms; other states' documents and timing must be checked separately.
Finalize the reviewed ownership and authority records. Keep the state confirmation, agreement, contribution records and relevant authorizations together so participants can identify both the entity and the arrangement they agreed to operate.
Confirm Federal Tax Classification
For federal income tax, a domestic LLC with two or more members generally defaults to partnership classification unless corporate treatment is elected. A single-member LLC generally defaults to disregarded-entity treatment unless corporate treatment is elected. Special circumstances and other taxes can affect the analysis.
Ask the tax adviser to confirm the actual classification, reporting obligations and treatment of proposed contributions and payments. Do not assume investment activity belongs on Schedule C, or that forming an LLC creates a deduction or tax advantage.
Apply for an EIN When Applicable
Check whether an EIN is needed for the entity's circumstances and the chosen accounts. The IRS issues EINs without a fee and directs LLC organizers to complete state formation first. Confirm application eligibility and retain the confirmation.
Separate the federal requirement from an institution's account-opening conditions. Do not assume every solo LLC has identical tax or account requirements.
Verify Accounts and Funding Readiness
Before transferring money, ask the selected bank or brokerage for its entity-account requirements. Verify the documents and authorized persons it needs; do not rely on a universal account-document list.
- Confirm the account is correctly titled for the arrangement.
- Confirm the institution has the required entity, identity and authority records.
- Record who contributes, what they contribute and how the transfer will be documented.
- Resolve any applicable legal, tax or transaction review conditions before funding.
- Keep entity activity distinguishable from personal activity in accounts and records.
Real estate investors should review property, financing and transfer questions before treating an asset move as a routine account transfer. This checklist does not authorize a deed, loan or retirement-account transaction.
Can You Pay Yourself or Transfer Money Out?
A bank transfer is not, by itself, an answer about payment authorization or tax treatment. Before moving money to a personal account, identify the owner, tax classification, purpose of the payment, approval required and records to retain.
Do not assume every payment is salary, every owner may withdraw unilaterally, or every transfer is tax-free. Ask the tax adviser how the proposed payment should be treated, and check it against the agreement and institution's conditions.
For co-owners, agree the practical process: who requests a payment, who approves it, how available cash is assessed and how the payment is recorded. For a solo arrangement, retain the same clarity about purpose and records. The aim is a repeatable funds-flow process, not an unexplained transfer that someone must reconstruct later.
Operate the Arrangement, Not Just the Entity
Common mistakes to avoid include leaving authority undocumented, mixing entity and personal records, overlooking applicable deadlines, and changing participation without revisiting the arrangement. Use a recurring check rather than relying on the formation confirmation alone.
- Maintain separate, understandable transaction and contribution records.
- Keep account access and investment authority consistent with the agreed terms.
- Calendar the obligations you verified with the applicable state, institutions and advisers.
- Revisit the arrangement before adding passive participants or paid management.
- Review planned financing, asset transfers and exits before executing them.
- Make sure owners know where records are kept and whom to contact when a decision is unresolved.
These practices are operational decision aids. They are not a guarantee of liability protection or compliance with every applicable rule.
Proceed, Prepare or Pause
End with a specific action, not a vague feeling that you should form an LLC.
Your position | Your outcome | What to do next |
|---|---|---|
You can explain the entity's purpose, have resolved review conditions, agreed essential terms and verified costs and requirements | Proceed | Follow the selected state's filing process, then verify accounts and funding readiness |
The structure may fit, but costs, authority, documents or transaction facts remain unresolved | Prepare | Gather the missing facts and resolve the named decision before filing or funding |
Passive capital, solicitation, paid management or a sensitive asset transaction needs specialist analysis | Pause the affected action | Take the proposed arrangement and participant roles to the appropriate counsel or tax adviser |
You cannot identify a meaningful problem the LLC would solve | Reconsider formation | Compare the existing arrangement and relevant alternatives before committing to an entity |
You can explain the entity's purpose, have resolved review conditions, agreed essential terms and verified costs and requirements
Proceed
Follow the selected state's filing process, then verify accounts and funding readiness
The structure may fit, but costs, authority, documents or transaction facts remain unresolved
Prepare
Gather the missing facts and resolve the named decision before filing or funding
Passive capital, solicitation, paid management or a sensitive asset transaction needs specialist analysis
Pause the affected action
Take the proposed arrangement and participant roles to the appropriate counsel or tax adviser
You cannot identify a meaningful problem the LLC would solve
Reconsider formation
Compare the existing arrangement and relevant alternatives before committing to an entity
Before money moves, can you explain whose money it is, who controls it, what obligations apply and which next action is appropriate? If not, name the unresolved question. A deliberate pause or a better-defined arrangement can be a useful result of this guide.
Legal.com Liability Disclaimer
All content published by Legal.com is provided for general informational purposes only. It is not legal advice, does not constitute a legal opinion, and should not be relied upon as a substitute for consultation with a qualified attorney. No attorney-client relationship is created by reading this article, using Legal.com templates, or contacting Legal.com. Legal.com disclaims all liability for actions taken or not taken based on this publication.